

Effective money management starts with clear habits that protect against unexpected costs, reduce costly debt, and build long-term security. Many households struggle with insufficient emergency savings, high-interest balances, and inconsistent budgeting, yet practical steps can improve financial stability without requiring extreme changes. Focusing on a realistic budget, an accessible cash reserve, prioritized debt reduction, and automated saving creates a foundation that supports both daily needs and future goals.
Create a Realistic Budget That Matches Your Life
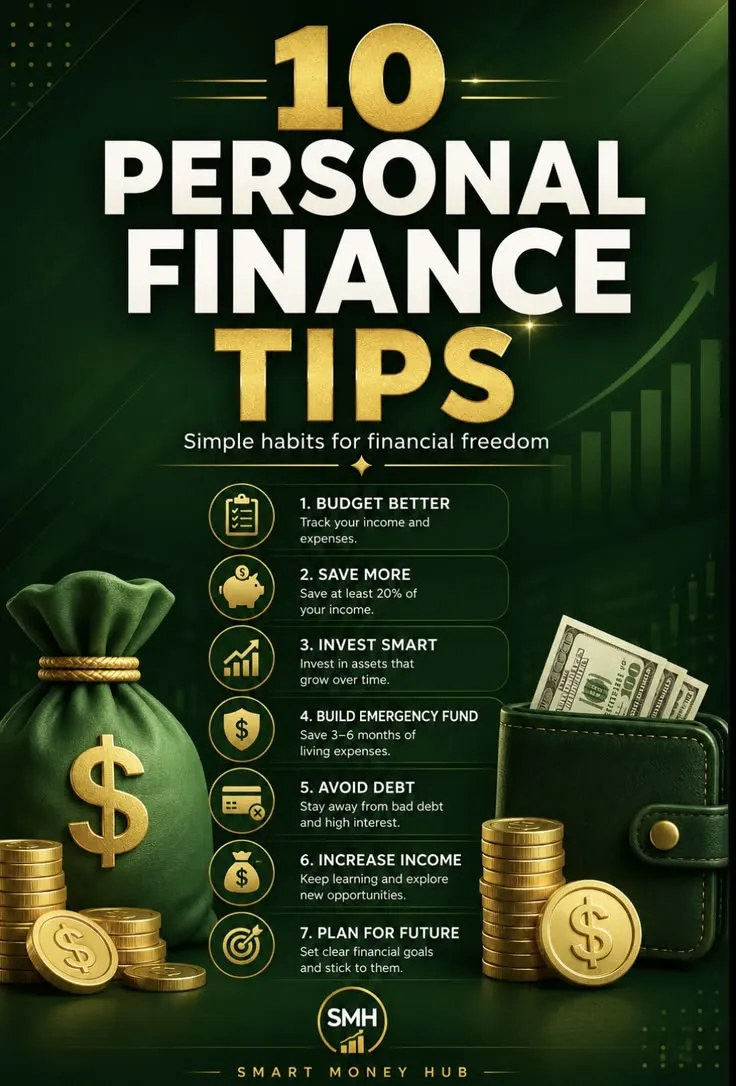
Begin by tracking income and expenses for at least one full month to see where money actually goes. Identify fixed costs such as housing, utilities, transportation, and groceries, then review flexible spending that can be adjusted. A widely used framework allocates roughly 50 percent of after-tax income to needs, 30 percent to wants, and 20 percent to savings and extra debt payments. If essential costs exceed half of income, a more flexible split such as 60/30/10 can still provide structure while remaining achievable.
Set specific, measurable, achievable, relevant, and time-bound goals. Instead of a vague intention to “save more,” define targets such as contributing a set percentage of salary to a retirement account each month or building a defined cash reserve by a certain date. Review the budget regularly and adjust for irregular expenses by setting aside small monthly amounts for annual or semi-annual costs. Canceling unused subscriptions and pausing non-essential services often frees money quickly without major lifestyle disruption.
Build an Emergency Fund for Financial Stability
An emergency fund covers unexpected expenses such as medical bills, car repairs, or temporary income loss without relying on high-interest credit. Experts commonly recommend three to six months of essential living expenses held in a liquid, accessible account. Households with variable income or greater risk factors may aim higher. Many people fall short of this target, with a significant portion unable to cover even a $1,000 emergency from savings alone.
Start small if needed. A starter reserve of one month’s expenses or a modest fixed amount provides immediate protection and builds momentum. Keep the fund in a high-yield savings account rather than a low-interest checking or traditional savings account so the money earns more while remaining available. Automate transfers on payday so the contribution happens before spending decisions arise. This “pay yourself first” approach turns saving into a default rather than an afterthought.
Address High-Interest Debt Strategically
Carrying balances on credit cards or other high-rate loans can cost far more than most savings accounts earn. Average credit card rates remain elevated, making aggressive payoff a high-return priority once minimum payments and a basic emergency buffer are in place. Two common methods work well depending on personality. The avalanche approach targets the highest-interest debt first to minimize total interest paid. The snowball method focuses on the smallest balance first, generating quick wins that sustain motivation.
List all debts with balances and interest rates, continue making minimum payments on everything, and direct extra money to the priority debt. After eliminating high-interest balances, redirect those payments toward building the full emergency fund or other goals. Capturing any available employer retirement match is also valuable, as it represents an immediate return that is difficult to match elsewhere.
Automate Saving and Begin Investing Consistently
Once a basic emergency fund exists and high-interest debt is under control, automate contributions to longer-term savings and retirement accounts. Consistent, modest amounts invested over time benefit from compounding. Low-cost broad index funds are frequently recommended for ordinary investors seeking diversified market exposure without the need to pick individual stocks. Tax-advantaged accounts such as workplace retirement plans or individual retirement accounts can improve after-tax growth.
Track net worth periodically by listing assets and liabilities. This provides a clearer picture of progress than focusing solely on monthly cash flow. Diversify across account types and asset classes according to time horizon and risk tolerance, and avoid putting all resources into a single investment.
Develop Sustainable Daily Habits
Review spending regularly to catch lifestyle creep early. Pause before non-essential purchases and consider a short no-spend period to reset habits. Shop around for better rates on insurance, banking, and utilities. Use rewards cards only if balances are paid in full each month. Small, consistent actions—such as redirecting a canceled subscription payment into savings—compound into meaningful results over time.
Prioritize financial decisions in a logical order: cover essential bills, establish a starter emergency reserve, capture employer matches, eliminate high-interest debt, expand the emergency fund, and then increase long-term investing. This sequence reduces the risk that one setback undoes previous progress.
Smarter money management does not require perfection or complex strategies. It requires consistent tracking, realistic budgeting, protection against surprises, disciplined debt reduction, and automated progress toward goals. Households that adopt these practices gain greater flexibility, lower financial stress, and a clearer path toward long-term security.
Read more – gloryhouseworld.com